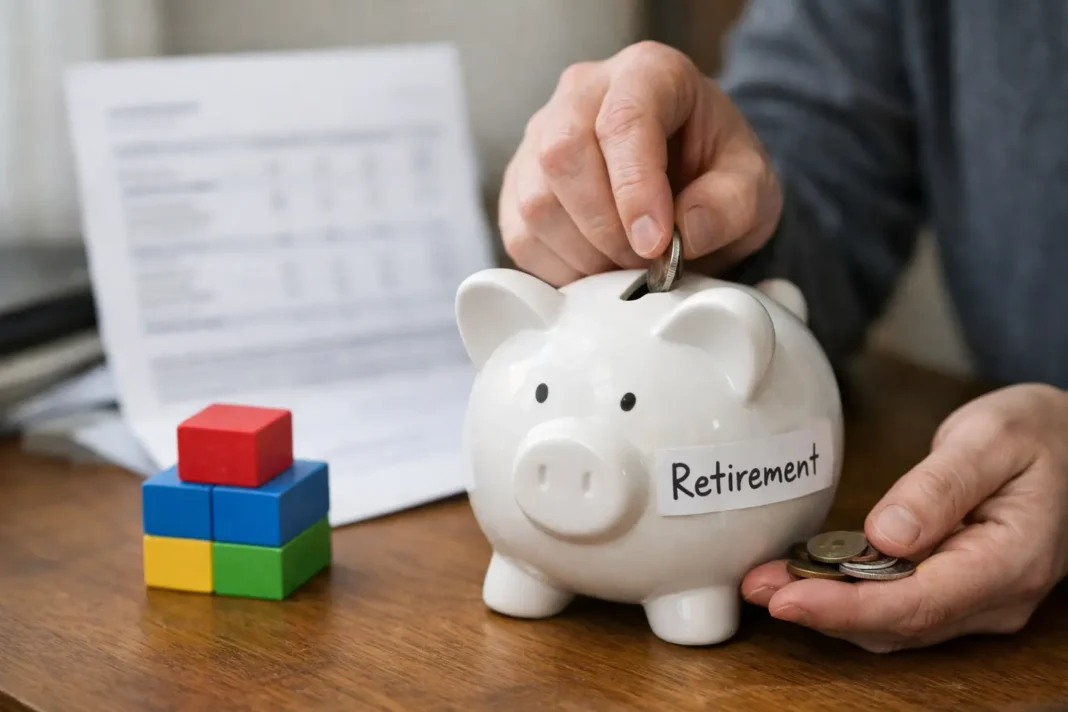

Parents are increasingly choosing to place small, regular contributions into long-term retirement accounts for their toddlers and babies. The practice, driven by the logic of a very long investment horizon, aims to harness compound growth over decades. Families who take this route typically describe it as a way to build a financial head start for adulthood while keeping funds locked away until retirement.
The specifics of these arrangements vary by market and provider. Some parents open child-named retirement plans that operate like standard workplace schemes, while others use accounts or products designed specifically for minors. Whatever the vehicle, the core idea is the same: early, consistent funding of a retirement-style pot that will not be readily available for discretionary spending in teenage years or early adulthood. Readers interested in the broader topic can find related coverage under pensions.
Financial advantages commonly cited for this approach include the long time horizon for investments to grow and the potential to access lower-cost, diversified funds suitable for decades-long strategies. Depending on local rules, some plans may also offer tax or allowance benefits; these depend on national regulation and individual circumstances. Keeping money in a locked account until retirement can also reduce the risk that a child will draw down savings prematurely.
There are trade-offs parents should weigh. Money earmarked for retirement cannot typically be redirected for nearer-term needs such as education or a first home, and future changes to tax or pension regulation could alter anticipated outcomes. Investment returns are not guaranteed and fees can erode long-term growth if not managed. Families should also consider how such funds interact with other household priorities and any means-tested benefits.
For parents considering this option, the practical next steps are to assess affordability, compare product charges and investment approaches, and seek guidance tailored to their jurisdiction. Consulting a regulated financial professional or official guidance can clarify tax rules and access conditions; for broader household planning, look into complementary savings and investment options to ensure a balanced approach.