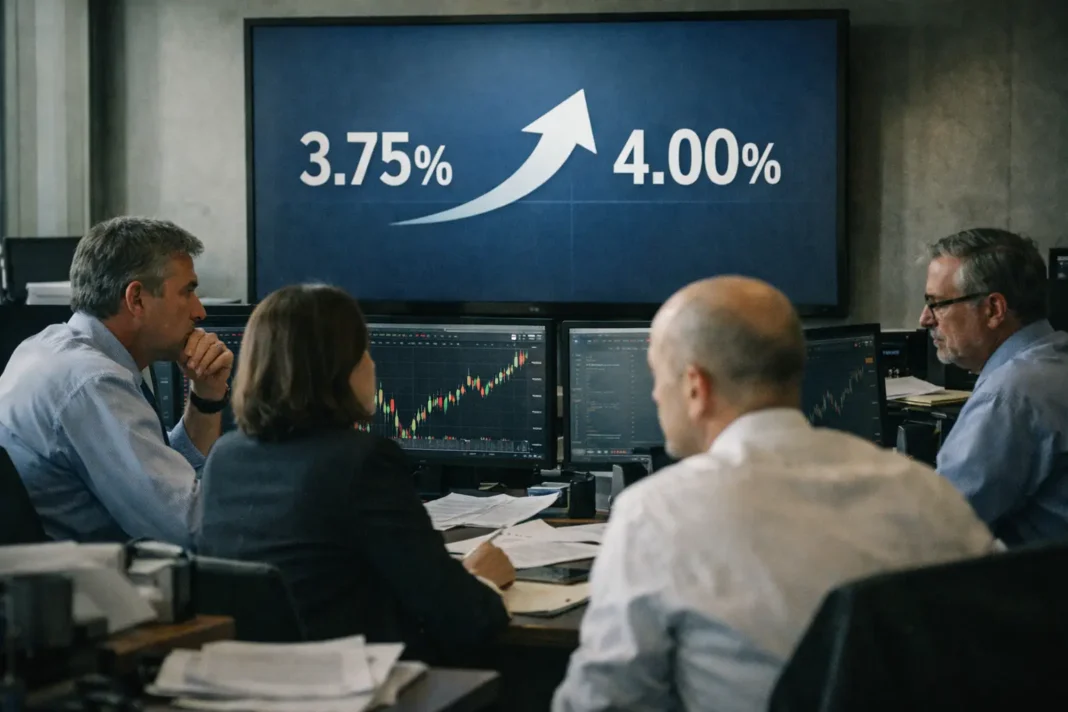

Interest rates are expected to rise for the first time in more than three years, with most analysts anticipating an increase from 3.75% to 4%. The projected quarter-point move would end a prolonged period without an upward adjustment and would bring borrowing costs back into focus for households, companies and financial markets.
The expected rise is modest in size but significant in direction. A move of 25 basis points would indicate a shift in the stance of monetary policy, especially after more than three years in which rates did not increase. For analysts, the level itself matters less than the signal it sends: policymakers may be preparing to respond to conditions that no longer support keeping rates unchanged.
Higher interest rates can affect the economy through several channels. New loans generally become more expensive, variable-rate borrowing may adjust, and companies can face higher financing costs when seeking credit or refinancing debt. Savers, by contrast, may benefit if banks pass on higher returns to deposits. The scale of the impact depends on how lenders react and whether the increase is followed by further policy moves.
Financial markets usually pay close attention not only to the rate decision itself, but also to the language that accompanies it. With most analysts already expecting a rise to 4%, the key issue is whether the move is presented as a one-off adjustment or as part of a broader tightening cycle. That distinction can influence expectations for future borrowing costs, investment decisions and market pricing.
If confirmed, the increase would represent the first upward step in more than three years and would mark a new phase after a long pause. The decision would arrive at a sensitive moment for borrowers and lenders alike, making the path of rates an important reference point for the wider economy in the months ahead.