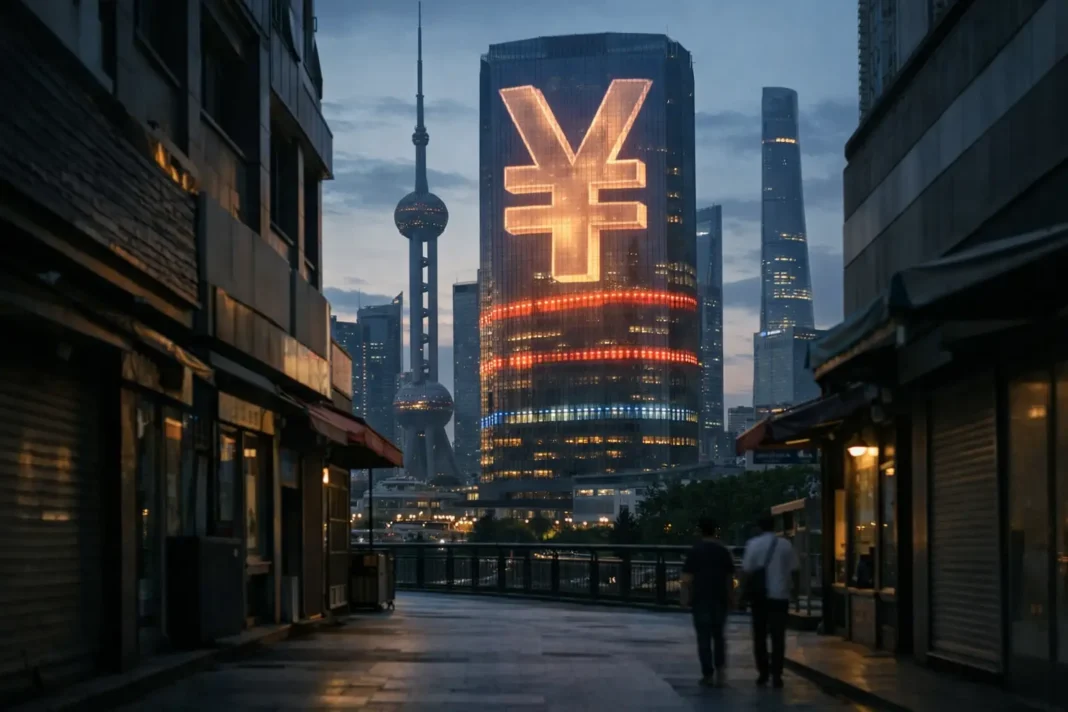

Currency debate centers on the widespread belief that the renminbi is undervalued and therefore a principal driver of global trade and financial imbalances. That view, repeated across markets and commentary, treats exchange-rate adjustment as a relatively quick remedy. But the currency’s current weakness also mirrors deeper weaknesses in domestic demand inside China, and moving straight to appreciation without tackling those fundamentals risks producing new distortions.
The link between subdued domestic spending and a weak currency is straightforward: when household consumption and investment remain soft, exporters seek external markets to sustain output, generating trade surpluses and associated capital flows. In that context a weaker exchange rate can help cushion a domestic slowdown by supporting export income. Policymakers therefore face a difficult trade-off between using currency settings to support short-term growth and taking steps that would reorient the economy toward stronger internal demand.
On the international stage, calls for a policy-driven revaluation of the renminbi tend to underestimate these trade-offs. A tighter focus on nominal exchange rates risks shifting the burden of adjustment onto other countries or amplifying volatility if Beijing’s domestic priorities—stimulating consumption, reforming social safety nets, or restructuring industry—are not advanced in tandem. International institutions such as IMF have argued for comprehensive strategies that combine macroeconomic and structural measures rather than reliance on a single instrument.
Practical consequences are clear: without measures that boost household purchasing power and address supply-side rigidities, a stronger renminbi could slow China’s recovery and merely redistribute external imbalances rather than resolve them. Durable correction of global imbalances therefore depends on coordinated policies—domestic reforms in China, demand support in deficit economies and multilateral cooperation—rather than a narrow focus on exchange-rate levels alone. Observers and policymakers looking for sustainable adjustment will need to prioritize those broader levers alongside any currency considerations.